Beware of “Rogue” Research & Development Consultants

Beware of “Rogue” Research & Development Consultants:

In recent years HMRC have identified and successfully challenged a number of spurious claims for Research and Development (R&D) tax credit relief made by purported ‘R&D Consultants’.

Many of these claims have been for projects that did not satisfy the criteria for the tax relief and some included overstated expenditure and consequently have been abusing the scheme.

The R&D rules offer legitimate claims generous tax breaks. For a company that is a Small or Medium-sized Entity (SME), qualifying expenditure attracts a tax deduction of 230% of the amount spent which can then be traded in for a tax refund of 14.5% if the company is loss making. Thus £100,000 of qualifying R&D expenditure would potentially result in a tax refund to a loss-making company of £33,350. Most R&D consultants charge a fee based on the amount of the claim.

To qualify for R&D relief, the expenditure must be incurred as part of a specific project to make an advance in science or technology. The project must relate to the company’s trade – either an existing one, or one that the directors intend to start up, based on the results of the R&D.

Further, the company must be able to explain how a project:

  • looked for an advance in science and technology;
  • had to overcome uncertainty;
  • tried to overcome this uncertainty; and
  • could not be easily worked out by a professional in the field.

In summary, R&D claims are often very worthwhile, but a number of strict requirements must first be met. If you are approached by an R&D Consultant or otherwise believe you may be incurring eligible R&D expenditure, please talk to us and we will help you file a compliant claim.

Need more information?

Do you need a trusted R&D Tax Relief Consultant for your business?

If you want to learn about how we can help you make a claim, or simply want some tax advice you can rely on, then please don’t hesitate to contact us. You can fill out a form below or call us on 0161 962 1855.

54 mile charity hike for ABF The Soldiers’ Charity

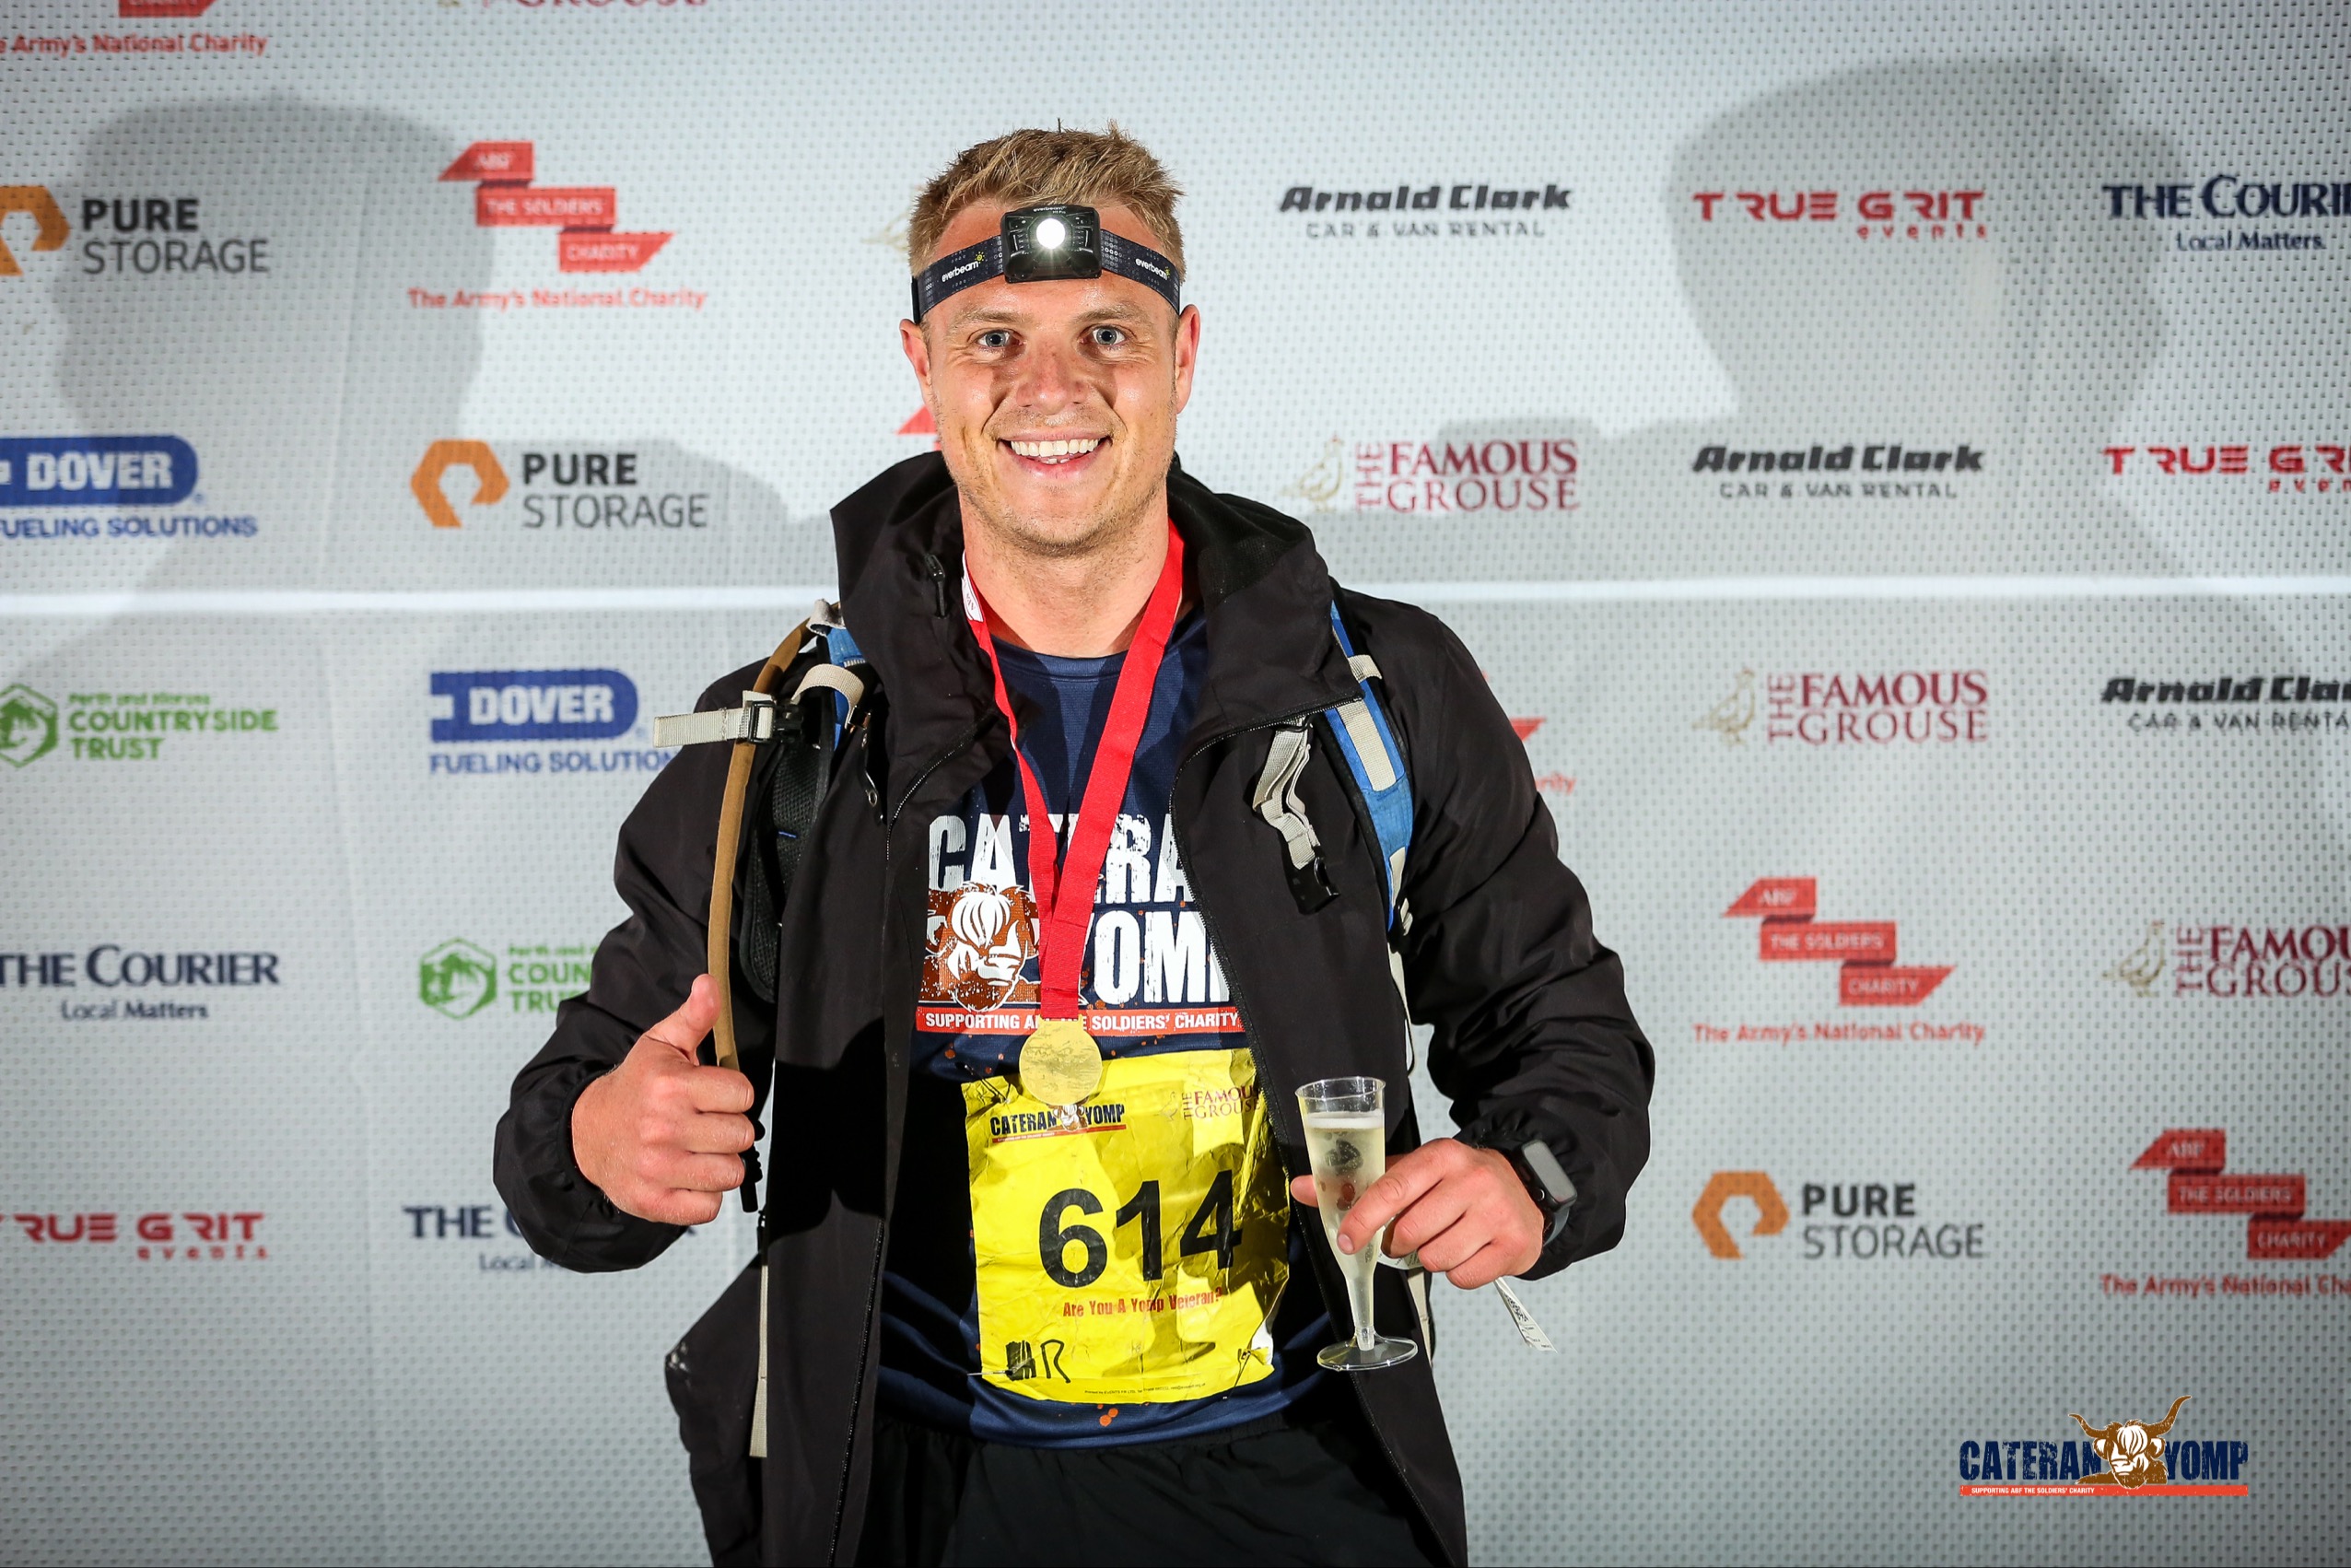
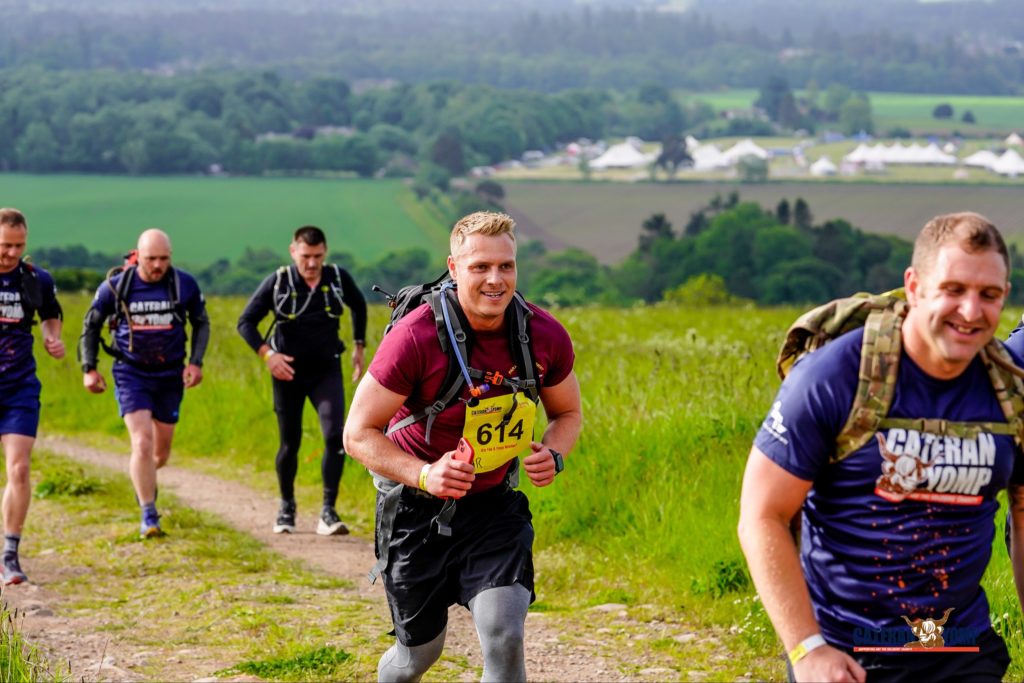
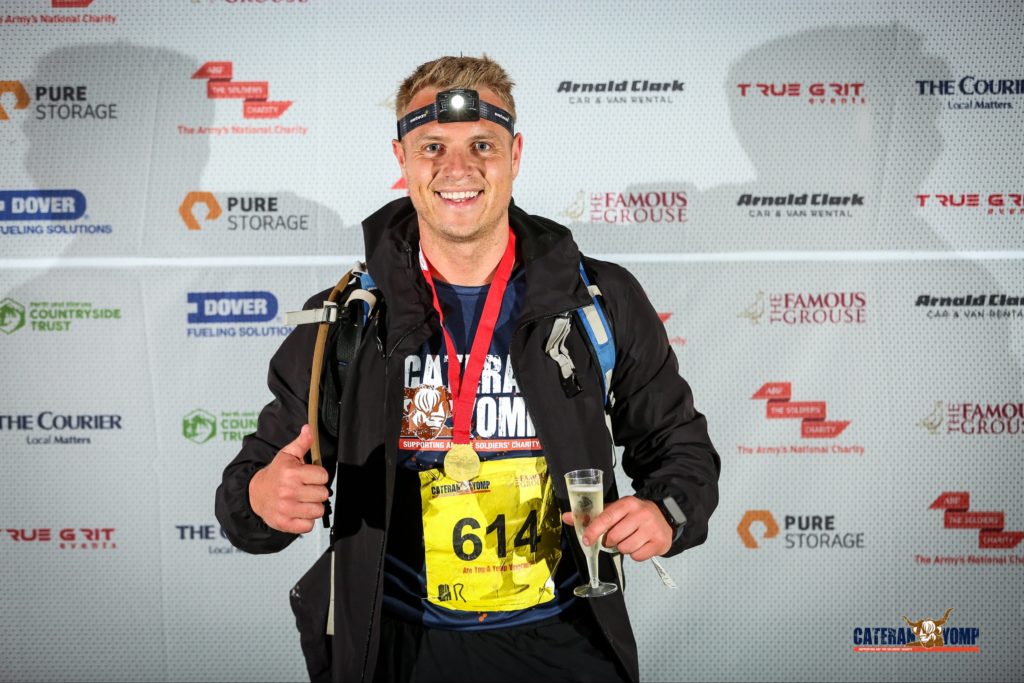
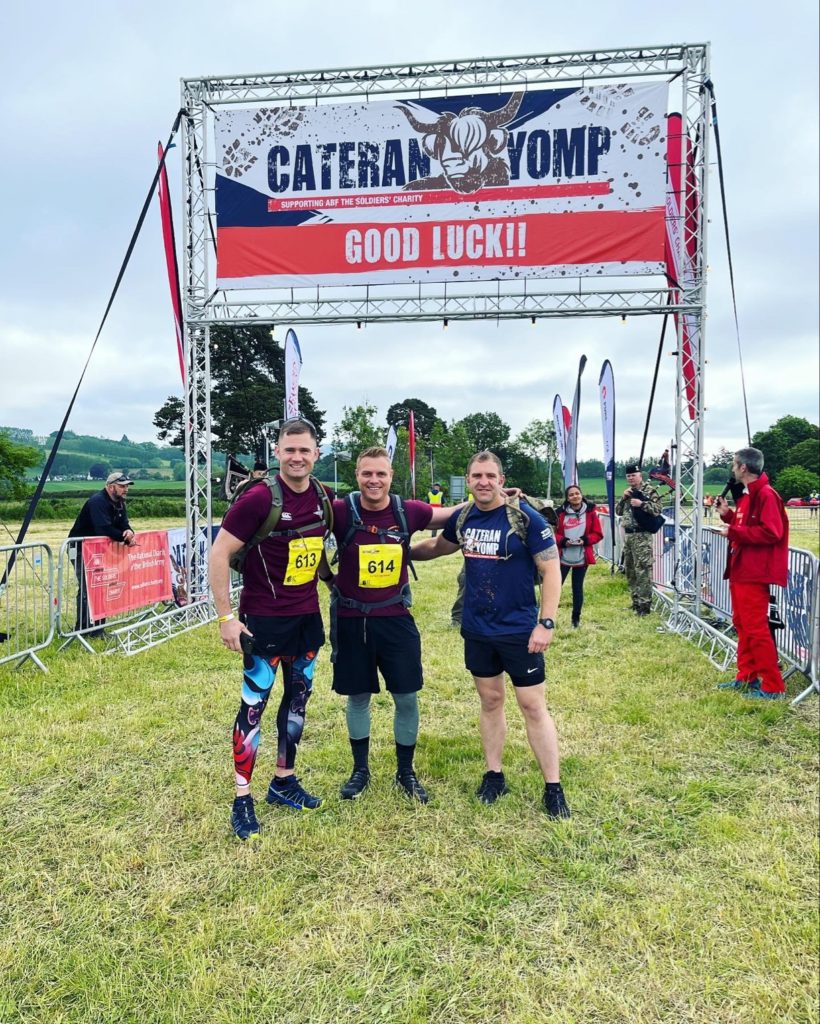
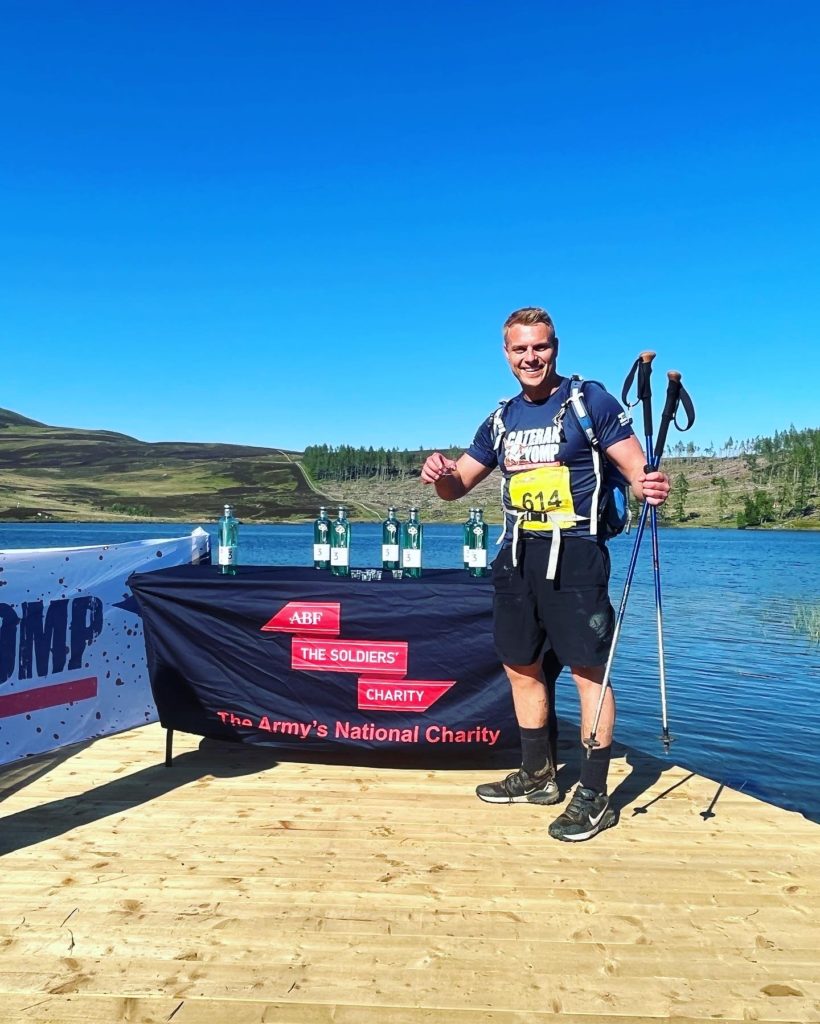
On the 4th-5th June 2022, Client Manager, Mikey took part in a charity hike in The Cateran Yomp. A 54-mile hike in 24 hours across rural Perthshire.

It was tough but he completed it and raised vital funds for ABF The Soldiers’ Charity, the Army’s National Charity, providing a lifetime of support to soldiers, veterans and their immediate families. Mikey raised a fantastic £829 + 106.90 Gift Aid. We were delighted to support him on this charity hike and look forward to more with the team in the future!

Well done Mikey from all the team at A&C!

Need more information?

Remember, if your business gets involved in a charity hike this can be tax efficient. We offer a wide range of services which are unique to your businesses who are just getting going! Our team of chartered accountants have a wealth of experience in a broad range of sectors, from construction and property to the charity sector. Our team work hard to ensure they create smart and effective tax-efficient solutions for start-ups to optimise growth and help them succeed. If you want to learn more about how the team can help or simply want some start-up advice from a trusted accountant do hesitate to contact us. For more information please do hesitate to contact us on 0161 962 1855. Alternatively you can email us using the form below and we will contact you as soon as possible.

Our fantastic team at A&C Chartered Accountants are here to help.

Small firms struggle to get finance

Small firms struggle to get finance:

A recent study by the Federation for small businesses (FSB) shows lending to small businesses has hit an all-time low. New findings from the quarterly Small Business Index (SBI) show successful finance applications plummeting to lowest level on record.

The FSB warns that banks “pulling up the drawbridge” to small firms will further stifle economic growth. Fewer than one in ten (9%) small firms applied for finance in Q1 2022, the lowest proportion since SBI records began. The share that saw applications approved (43%) is also at a record low. Of the few firms that did manage to secure finance, four in ten (42%) plan to use credit to manage cashflow, considerably more than the numbers planning to use funds for equipment updates (21%), expansion (19%) or recruitment (4%).

Please talk to us if you need finance – we can help!

See: Lending to small businesses hits all-time low, new study finds, with six in ten impacted by late payment | FSB, The Federation of Small Businesses

Need more information?

We work with many small firms? We offer a wide range of services which are unique to your business. Our team of chartered accountants have a wealth of experience in a broad range of sectors, from construction and property to the charity sector. Our team work hard to ensure they create smart and effective tax-efficient solutions for small firms and start-ups to optimise growth and help them succeed. If you want to learn more about how the team can help or simply want some start-up advice from a trusted accountant do hesitate to contact us. For more information please do hesitate to contact us on 0161 962 1855. Alternatively you can email us using the form below and we will contact you as soon as possible.

Our fantastic team at A&C Chartered Accountants are here to help.

Workplace Charging Scheme: guidance for charities and small accommodation businesses

Workplace Charging Scheme:

The UK Government is now offering help to businesses with the upfront costs to install charge points.

The Workplace Charging Scheme (WCS) is a voucher-based scheme that provides eligible applicants with support towards the upfront costs of the purchase and installation of electric vehicle (EV) chargepoints.

The scheme is available for B&Bs, campsites, small hotels, charities and any other accommodation business with less than 250 employees.

For more information please follow the link here: Workplace Charging Scheme: guidance for charities and small accommodation businesses – GOV.UK (www.gov.uk

Need more information?

Do you need further guidance on the Workplace Charging Scheme?We offer a wide range of services which are unique to your business. Our team of chartered accountants have a wealth of experience in the hotel and charity sectors. Our team work hard to ensure they create smart and effective tax-efficient solutions for start-ups to optimise growth and help them succeed. If you want to learn more about how the team can help or simply want some start-up advice from a trusted accountant do hesitate to contact us. For more information please do hesitate to contact us on 0161 962 1855. Alternatively you can email us using the form below and we will contact you as soon as possible.

Our fantastic team at A&C Chartered Accountants are here to help.

Understanding scale rate payments

Understanding scale rate payments:

As an employer providing business or private expenses for your employees, you have certain tax, National Insurance and reporting obligations.

The rules on cash sum payments for business expenses cover:

  • cash sums you provide to meet the costs of your employees’ expenses
  • expenses they’ve paid for themselves that you reimburse
  • scale rate payments’ you pay at a level agreed with HM Revenue and Customs (HMRC)
  • round sum allowances’, which you give to an employee regardless of how they spend them

Scale rate payments

If you provide your employees with a set amount of cash to pay for some common business expenses like travel and meals, these are known as ‘scale rate payments’.

As long as your employee has actually spent the scale rate payment on business expenses, you will not need to check every single receipt – it’s fine to just check a sample.

You can set up a scale rate payment by either:

HMRC also provides benchmark rates for employees travelling outside the UK.

What to report and pay

You must report the scale rate payments on form P11D unless they are exempt or no more than the agreed scale rate or benchmarked scale rate. This means you do not have to include them in your end-of-year reports.

You do not need to deduct or pay any tax or National Insurance when reporting scale rate payments.

There are separate rules for individual benefits you provide to your employees. You need to follow specific reporting and payment rules for different items, including travelmeals and accommodation.

Payments for private expenses count as earnings.

Need more information?

We offer a wide range of services which are unique to your businesses who are just getting going! Our team of chartered accountants have a wealth of experience in a broad range of sectors, from construction and property to the charity sector. Our team work hard to ensure they create smart and effective tax-efficient solutions for start-ups to optimise growth and help them succeed. If you want to learn more about how the team can help or simply want some start-up advice from a trusted accountant do hesitate to contact us. For more information please do hesitate to contact us on 0161 962 1855. Alternatively you can email us using the form below and we will contact you as soon as possible.

Our fantastic team at A&C Chartered Accountants are here to help.

Should you convert a property to a furnished holiday let?

Should you convert a property to a furnished holiday let?

Normally a residential rental property would be subject to a 28% capital gains tax (CGT) rate on its disposal. However, if it qualifies as a furnished holiday let (FHL) then the capital gains tax rate can be reduced to 10% by taking advantage of Business Asset Disposal Relief (BADR). It may be possible to make a non-FHL into an FHL for the two years prior to disposal and then enjoy BADR on the whole gain.

To qualify as an FHL, a property must be situated in the UK or the European Economic Area (EEA), it must be furnished and let on a commercial basis and the following conditions need to be satisfied:
1. The property must be available for letting for 210 days a year; and
2. It must actually be let for 105 days a year; and
3. The property must not normally be let for periods of more than 31 consecutive days to the same person, but if it is so let, those days do not count towards the 105 day total (above).

In the case of a single property, relief should be available if the property was used as an FHL for two years before the business ceased and the disposal takes place within three years of any cessation.

BADR may not be available when multiple FHLs are held and only some of them have been disposed. This is because HMRC will not automatically accept that this will be the disposal of the whole or part of a business (they say that it depends on the facts). When not all FHLs are sold then the risk is that HMRC resist a BADR claim on the basis that only business assets are being disposed of rather than a definable part of the business.
This all makes me think that in some cases it may be worth bringing a property within the FHL rules two years prior to a disposal.

Example: Giles owns a rental property in Devon which was purchased years ago for £200,000 and is now worth £1.2m. He now wishes to sell the property and is told that he would face a tax liability of £280,000 (£1m at 28%) if he did so. However, if he were to run an FHL business for at least two years then (all things being equal) this tax liability could be reduced to £100,000 (£1m at 10%).

Forbes Dawson view

Although changing a property to an FHL is a significant commercial decision, there can be significant tax savings achieved in doing so because BADR can be enjoyed on the whole gain even when the FHL status has only applied over a relatively short period of ownership. Also, with the rise of websites such as Airbnb, it is now likely to be quite straightforward to set up a qualifying FHL business.

If you have any questions on the above, please do not hesitate to get in touch.

Need more information?

Should you convert a property to a furnished holiday let?

Our team of property accountants can help you answer that question, taking into account your goals and current situation.

We work hard to create smart and effective tax-efficient solutions for our clients. If you want to learn more about how we can help, please contact us.

Capital gains tax on separation and divorce

Capital gains tax on separation and divorce:

When a married couple or civil partners separate, tax planning is understandably not at the top of the list of their thoughts. However, a ‘no gain/no loss’ rule allows capital assets to be transferred between them free of capital gains tax (CGT) up to the end of the tax year in which they permanently separate. Beyond that date, asset transfers between the couple will often give rise to a CGT liability. With many divorce settlements taking several months this is worth careful consideration.

The Office of Tax Simplification has recommended to the Treasury that the no gain/no loss rule should be extended to two years from the date of permanent separation. The government have accepted this recommendation, but the change in rules is yet to be legislated.

The actual date that assets are treated as transferred between the separating couple depends upon how the marriage or civil partnership is dissolved.

It is also important to consider private residence relief (PRR) on the family home. It should be noted that where one spouse or civil partner leaves the matrimonial home, they may continue to be eligible for PRR even if they no longer live in the property. There are specific conditions that need to be satisfied for this to apply.

All in all, CGT on separation is a complex area and please do talk to us if any issues may be in point. We understand the sensitivity of the situation and are here to help.

Need more information?

We offer a wide range of accountancy services, including capital gains tax advice.

If you want to learn more about how our team can help or simply want some start-up advice from a trusted accountant don’t hesitate to contact us. Call us on 0161 962 1855 or fill in the form below and we will contact you as soon as possible.

Salary sacrifices – make sure you get the timing right

Salary sacrifices – make sure you get the timing right:

Many employers and employees have been putting in place salary sacrifice arrangements to give up some of their contractual salary in exchange for additional pension contributions or an electric company car. In these specific cases and if correctly structured, the employee is taxed on the lower of the taxable benefit and the salary foregone.

In the case of the electric car the benefit is currently 2% of the original list price. There is no taxable benefit on employer pension contributions.

When the director or employee enters into the salary sacrifice arrangement, they must agree with their employer to vary the employment contract well in advance of the date when the first payment under the new arrangement is due to be made. If the contractual changes have not been completed by that date, the terms of the previous contract continue to be in force.

This means that the employee is still entitled to receive, and is therefore still taxable on, the previous higher salary, even though the smaller, post- sacrifice amount is paid.

Need more information?

Do you need help with Salary sacrifices? We offer a wide range of services which are unique to your business. Our team of chartered accountants have a wealth of experience in a broad range of sectors, from construction and property to the charity sector. Our team work hard to ensure they create smart and effective tax-efficient solutions for start-ups to optimise growth and help them succeed. If you want to learn more about how the team can help or simply want some start-up advice from a trusted accountant do hesitate to contact us. For more information please do hesitate to contact us on 0161 962 1855. Alternatively you can email us using the form below and we will contact you as soon as possible.

Our fantastic team at A&C Chartered Accountants are here to help.

The Employment Allowance – Don’t forget to claim

The Employment Allowance (EA) is a £5,000 allowance set against employers National Insurance Contributions (NICs) and has to be claimed each tax year if the employer qualifies. This allowance was introduced in 2014/15 and was increased to £5,000 from 2022/23. Employers make a claim for the Employment Allowance through their payroll software. They do this by completing and submitting a Real Time Information – Employer Payment Summary (EPS) to HMRC. The employer must enter “Yes” in the “Employment Allowance Indicator” field of the EPS confirming that they are eligible to claim the allowance.

Eligible employers can claim the Employment Allowance at any time during a tax year. Employers may also claim the Employment Allowance against closed tax years, provided they have not already claimed the allowance for those years. However, claims for closed tax years are limited to the four tax years falling before the current tax year.

The Employment Allowance can be claimed by most employers who pay secondary Class 1 NICs on their employees. This includes:

  • businesses (includes self- employed persons, companies and partnerships who have employees)
  • charities (includes private businesses that have charitable status such as schools, academies, further education colleges and universities)
  • Community Amateur Sports Clubs

If two or more companies are connected with one another, or two or more charities are connected with one another, then only one of those companies/charities may claim the Employment Allowance and they must decide which company/charity claims the allowance.

For recently updated guidance on connected businesses see: –

https://www.gov.uk/hmrc-internal-manuals/national-insurance-manual/nim06560


Other Employers Excluded from claiming the Employment Allowance

Employers are not eligible to claim the Employment Allowance where their employers’ Class 1 National Insurance liabilities in the previous tax year exceeded £100,000.

Another important exclusion from EA are single director companies where the director is the sole employee of the company.

Employment Allowance counts towards the total de minimis State Aid you’re allowed to get over a 3 year period. Employers that exceed the de minimis State Aid threshold for their sector (Agriculture products for example 20,000 euros) are also excluded from claiming EA.

Need more information?

Do you need further support with your payroll?

Our team offers a complete range of payroll services for companies across all sectors, from charities to construction firms.

If you want to learn more about how the team can help, or simply want some start-up advice from a trusted accountant, don’t hesitate to contact us on 0161 962 1855. Alternatively, you can email us using the form below and we will contact you as soon as possible.

Treasury Starts Conversation to Reform UK Capital Allowance Regime

Treasury Starts Conversation to Reform UK Capital Allowance Regime

A publication aiming to kickstart a conversation with businesses about how to reform the UK’s capital allowances regime was published earlier this month.

The publication sets out how firms can work with the government on capital allowances to help foster a new culture of enterprise and growth in the UK, with responses requested by 1 July 2022.

The UK has a long-standing issue with productivity and one of the key underlying causes is a lack of capital investment.

According to OECD data, companies invest just 10% of GDP each year, compared with 14% in our competitor countries – our tax system doesn’t reward investment as much as other countries do.

The Spring Statement set out some illustrations of the types of changes government could make to the current capital allowances regime. This new guidance delves into those options in further detail, which includes:

  • increasing the permanent level of the Annual Investment Allowance
  • increasing the rates of Writing Down Allowances
  • introducing general First-Year Allowances (FYAs) for qualifying expenditure on plant and machinery
  • introducing an additional FYA
  • introducing permanent full expensing

While some business organisations have called for full expensing to be introduced following the super-deduction, this could cost over £11 billion a year. The government is keen to hear views as to whether that would be well targeted if funding is available, and if it isn’t available, how to best target their approach.

See:  Treasury Starts Conversation to Reform UK Capital Allowance Regime – GOV.UK (www.gov.uk)

Need more information?

Do you need further guidance on the Capital Allowance Regime? We offer a wide range of services which are unique to your business! Our team of chartered accountants have a wealth of experience in a broad range of sectors, from construction and property to the charity sector. Our team work hard to ensure they create smart and effective tax-efficient solutions for start-ups to optimise growth and help them succeed. If you want to learn more about how the team can help or simply want some start-up advice from a trusted accountant do hesitate to contact us. For more information please do hesitate to contact us on 0161 962 1855. Alternatively you can email us using the form below and we will contact you as soon as possible.

Our fantastic team at A&C Chartered Accountants are here to help.

End of tax year payroll procedures

End of tax year payroll procedures:

As the 2021/22 tax year has now ended, employers need to carry out the following end of year procedures:-

  • Provide employees with their P60 annual summaries by 31 May 2022,
  • Prepare forms P11D for employees’ expenses and benefits by 5 July 2022,
  • Update employees’ payroll data for 2022/23, in particular their new tax codes, and

Update their payroll software for 2022/23 if they haven’t already done so.

Need more information?

We have a dedicated in-house payroll team who control all of our clients payroll procedures. We offer a wide range of services which are unique to your business and our team of chartered accountants have a wealth of experience in a broad range of sectors, from construction and property to the charity sector. Our team work hard to ensure they create smart and effective tax-efficient solutions for start-ups to optimise growth and help them succeed. If you want to learn more about how the team can help or simply want some start-up advice from a trusted accountant do hesitate to contact us. For more information please do hesitate to contact us on 0161 962 1855. Alternatively you can email us using the form below and we will contact you as soon as possible.

Our fantastic team at A&C Chartered Accountants are here to help.

Stamp duty land tax possible changes

HMRC have been consulting on changes to the relief from stamp duty land tax (SDLT) when two or more properties are acquired at the same time. This indicates that a change in the rules is imminent, and purchasers should take advantage while the relief continues to apply.

Currently where at least two dwellings are purchased in a single transaction, or as part of a series of linked transactions between the same vendor and purchaser, the purchaser can choose to have the rate of SDLT determined by the average value of the dwellings purchased, rather than their combined value. Purchasers can therefore benefit from multiple nil-rate and lower percentage bandings, significantly reducing the amount of SDLT payable. Multiple dwellings relief doesn’t apply automatically; it must be claimed in a land transaction return and your solicitor may not be aware of this important relief.


Need more information?

Do you need further guidance on stamp duty land tax? We offer a wide range of services which are unique to your business. Our team of chartered accountants have a wealth of experience in a broad range of sectors, from construction and property to the charity sector. Our team work hard to ensure they create smart and effective tax-efficient solutions for start-ups to optimise growth and help them succeed. If you want to learn more about how the team can help or simply want some start-up advice from a trusted accountant do hesitate to contact us. For more information please do hesitate to contact us on 0161 962 1855. Alternatively you can email us using the form below and we will contact you as soon as possible.

Our fantastic team at A&C Chartered Accountants are here to help.

Annual Tax on Enveloped Dwellings

The Annual Tax on Enveloped Dwellings (ATED) was introduced in April 2012 and is charged where certain residential properties are owned within a corporate structure. This tax not only catches UK properties owned by wealthy oligarchs via offshore companies but also applies to UK resident companies. Originally the charge only applied where the value of the property exceeded £2 million but that threshold has been subsequently reduced to £500,000.

The charge for 2022/23 starts at £3,800 and rises to £244,750 where the property value is more than £20 million.

Properties need to be revalued every five years and the latest valuation date is 1 April 2022. With significant increases in property values in recent years this may mean that more companies may be required to complete an ATED return.

There are numerous exemptions and reliefs from ATED but companies still need to submit an ATED Relief Declaration Return.

MAIN ATED RELIEFS

The main situations where there is a relief from ATED are where the property is:-

  • let to a third party on a commercial basis
  • being developed for resale by a property developer
  • owned by a property trader as the stock of the business for the sole purpose of resale
  • a farmhouse occupied by a farm worker or a former long-serving farm worker

Need more information?

We offer a wide range of services which are unique to your businesses who are just getting going! Our team of chartered accountants have a wealth of experience in a broad range of sectors, from construction and property to the charity sector. Our team work hard to ensure they create smart and effective tax-efficient solutions for start-ups to optimise growth and help them succeed. If you want to learn more about how the team can help or simply want some start-up advice from a trusted accountant do hesitate to contact us. For more information please do hesitate to contact us on 0161 962 1855. Alternatively you can email us using the form below and we will contact you as soon as possible.

Our fantastic team at A&C Chartered Accountants are here to help.

Reimburse private fuel for your company car?

Reimburse private fuel for your company car?

Unless there is full reimbursement of fuel provided for the private use of a company car there is a benefit in kind charge based on a fixed figure of £24,600 which is multiplied by the CO2 emissions percentage that is used to calculate the company car benefit for that vehicle.

For a high emission car that percentage can be as high as 37%, resulting in a benefit in kind charge of £9,102 and an income tax bill of £3,640.80 for a higher rate taxpayer. Even with current fuel prices, that would be an awful lot of private mileage, so the employee should consider reimbursing the employer using the HMRC approved mileage rates by 5 July 2022 for 2021/22.

Need more information?

Do you need further guidance on private fuel and own a company car? We offer a wide range of services which are unique to your business. Our team of chartered accountants have a wealth of experience in a broad range of sectors, from construction and property to the charity sector. Our team work hard to ensure they create smart and effective tax-efficient solutions for start-ups to optimise growth and help them succeed. If you want to learn more about how the team can help or simply want some start-up advice from a trusted accountant do hesitate to contact us. For more information please do hesitate to contact us on 0161 962 1855. Alternatively you can email us using the form below and we will contact you as soon as possible.

Our fantastic team at A&C Chartered Accountants are here to help.

Super-deduction for equipment runs until March 2023

The 130% super-deduction for companies that invest in new plant and machinery applies where the expenditure is incurred between 1 April 2021 and 31 March 2023. Many companies recovering from the coronavirus pandemic have not had the resources to commit thus far and the war in Ukraine may have made them reluctant to invest until the political and economic situation stabilises. Thankfully the special tax relief announced in the Spring 2021 Budget will be available for expenditure up until 31 March 2023 potentially saving £247 for every £1,000 invested in new equipment.

It is hoped that the current £1 million Annual Investment Allowance (AIA) will continue to be held at that level once the super-deduction ends. Note that the AIA is available to unincorporated businesses as well as limited companies and for second hand as well as new equipment.

Need more information?

Do you need further support with the super-deduction tax relief? We offer a wide range of services which are unique to your business and our team of chartered accountants have a wealth of experience in a broad range of sectors, from construction and property to the charity sector. Our team work hard to ensure they create smart and effective tax-efficient solutions for start-ups to optimise growth and help them succeed. If you want to learn more about how the team can help or simply want some start-up advice from a trusted accountant do hesitate to contact us. For more information please do hesitate to contact us on 0161 962 1855. Alternatively you can email us using the form below and we will contact you as soon as possible.

Our fantastic team at A&C Chartered Accountants are here to help.

Trading losses – carry back or forward?

Trading losses – carry back or forward?

In the March 2021 Budget, it was announced that the normal one-year carry back for trading losses would be extended to three years. That means that many businesses that have made losses during the COVID-19 pandemic may be able to obtain a repayment of tax paid in that earlier three-year period. This enhanced carry back applies to unincorporated businesses as well as limited companies and will provide a much-needed tax refund.

However, with the corporation tax rate increasing to 25% from 1 April 2023 for profits over £250,000 it may be more beneficial to carry the loss forward. Note that the marginal rate is 26.5% where profits are between £50,000 and £250,000 a year. So, there is a trade-off between a tax refund now and a possible bigger tax saving in the future.

For the enhanced carry back the company’s loss-making accounting period must end between 1 April 2020 and 31 March 2022. For unincorporated businesses, the trading loss must be incurred in 2020/21 or 2021/22.

For corporation tax purposes, it is no longer necessary to finalise the year-end company accounts and file the CT600 corporation tax return to claim loss relief where the loss is no more than £200,000. HMRC will however require evidence of the loss to process the claim such as management accounts for the period.

Need more information?

Do you need further guidance on trading losses?

Our team of corporation tax specialists have a wealth of experience in a broad range of sectors. We work hard to create smart and effective tax-efficient solutions for start-upsSMEs and beyond.

If you want to learn more about how the team can help, please fill in a contact form or call 0161 962 1855.

Changes to VAT rates from 1 April 2022

Changes to VAT rates from 1 April 2022:

Many in the hospitality sector were hoping that the Chancellor would extend the 12.5% reduced rate that has applied since 1 October 2021 but, as scheduled, the rate has reverted to 20% from 1 April 2022.

The increase applies to hospitality, visitor attractions, catering services including restaurants and takeaways.

This has a consequential effect on the VAT Flat Rate Scheme percentages from 1 April 2022 onwards as set out below:

Type of Business From 1 April 2022
Catering services including restaurants and takeaways 12.5%
Hotel or accommodation 10.5%
Pubs 6.5%

Need more information?

Do you need further guidance on the changing VAT rates?

Our VAT advisors have a wealth of experience in a broad range of sectors, from construction and property to the charity sector.

If you want to learn more about how the team can help or simply want some tax advice from a trusted accountant, please contact us by filling in a contact form or calling 0161 962 1855.

Business Support: Help to Grow: Digital Scheme

‘Help to Grow: Digital’ is a UK-wide scheme to help small and medium-sized businesses adopt digital technologies that are proven to increase productivity.

The scheme offers:

  • free, impartial advice and guidance about what digital technology is best suited to your business and how it can boost your business’ performance
  • targeted financial support, if your business is eligible, worth up to £5,000 towards the costs of buying approved digital technologies

The website offers advice, guidance and tools to help businesses explore the huge potential of digital technology to help your business to grow. It aims to help you:

  • identify the digital technology needs of your business
  • make informed decisions about which software products best meet those needs
  • successfully incorporate these products into your business

See: Help to Grow: Digital (learn-to-grow-your-business.service.gov.uk)

Need more information?

Are you interested in the Help to Grow scheme? We offer a wide range of services which are unique to your business. Our team work hard to ensure they create smart and effective tax-efficient solutions for start-ups to optimise growth and help them succeed. If you want to learn more about how the team can help or simply want some start-up advice from a trusted accountant do hesitate to contact us. For more information please do hesitate to contact us on 0161 962 1855. Alternatively you can email us using the form below and we will contact you as soon as possible.

Our fantastic team at A&C Chartered Accountants are here to help.

The Small Business Sustainability Basics Programme

Small Business Britain is launching “The Sustainability Basics programme”, in partnership with Oxford Brookes Business School, to help small businesses make the most of the opportunities of sustainability.

This free programme (and community of like-minded businesses) will give each entrepreneur the basics they need to supercharge their sustainability planning, reduce their impact on the planet, and turn their sustainability plans into fantastic commercial advantage.

This programme will be delivered over six weeks entirely via digital channels.

Webinars are recorded and available for catch up on a dedicated page on the Small Business Britain website.

All sessions begin at 11am and the modules include:

  1. 21 March 2022: Sustainability is Good for Business
  2. 28 March 2022: Starting at the Beginning: Energy and Transport
  3. 4 April 2022: Where You Are & What You Do
  4. 25 Apr 2022: A Team Effort: Working With & Adapting Your Supply Chain
  5. 3 May 2022: Offsetting: The Good, The Bad & Making a Plan
  6. 9 May 2022: Sustainability for You

See:  Small Business Britain | Champion. Inspire. Accelerate.


Need more information?

Are you interested in the Sustainability Basics programme? We offer a wide range of services which are unique to your business. Our team of chartered accountants have a wealth of experience in a broad range of sectors, from construction and property to the charity sector. Our team work hard to ensure they create smart and effective tax-efficient solutions for start-ups to optimise growth and help them succeed. If you want to learn more about how the team can help or simply want some start-up advice from a trusted accountant do hesitate to contact us. For more information please do hesitate to contact us on 0161 962 1855. Alternatively you can email us using the form below and we will contact you as soon as possible.

Our fantastic team at A&C Chartered Accountants are here to help.

Personal Allowance 2021/22 – don’t lose it!

Personal Allowance 2021/22 – don’t lose it!

For every £2 that your adjusted net income exceeds £100,000 the £12,570 personal allowance is reduced by £1. Pension contributions and Gift Aid can help to reduce adjusted net income and save tax at an effective rate of 60%. The restriction applies between £100,000 and £125,140 adjusted net income.

Consider a salary sacrifice scheme

Another way that you could avoid the personal allowance trap and also reduce income tax and national insurance would be to agree with your employer to sacrifice some of your salary in exchange for a tax free, or low tax benefits in kind. Common examples would be additional pension contributions or providing an electric company car in exchange for a lower salary.

We can assist you in setting up a salary sacrifice arrangement correctly as it will involve amending the contract of employment. You may be doing this anyway as many employers are moving to “hybrid” working and changing the days that staff are required to work in the office.

Need more information?

Do you need further guidance on how you can avoid losing your Personal Allowance 2021/22?

We offer a wide range of tax services which are unique to you and your business. Our team of chartered accountants have a wealth of experience in a broad range of sectors, from construction and property to the charity sector. Our team work hard to ensure they create smart and effective tax-efficient solutions for start-ups to optimise growth and help them succeed. If you want to learn more about how the team can help or simply want some start-up advice from a trusted accountant do hesitate to contact us. For more information please do hesitate to contact us on 0161 962 1855. Alternatively you can email us using the form below and we will contact you as soon as possible.

Our fantastic team at A&C Chartered Accountants are here to help.

Changes to accounting for VAT registered importers

HMRC have recently updated their guidance for VAT registered importers. These traders must account for postponed import VAT on their VAT returns for the accounting period which covers the date they imported the goods. The normal rules apply for what VAT can be reclaimed as input tax and the trader’s monthly statement will contain the information to support their claim.

HMRC is aware of the problems some importers are having when trying to access their monthly VAT statements. If you cannot access your statement or you’re having problems when viewing your statement, you can estimate your import VAT figures for the months you cannot access statements for. Your estimate should be as accurate as possible, based on the amount you’ve paid for the goods and any other costs you agreed to cover. As long as you take reasonable care to follow the guidance, there will be no penalty for errors.

There are also important changes from 1 June 2022 for small businesses using the Flat Rate Scheme who are importing goods and using postponed VAT accounting.

Need more information?

We offer a wide range of VAT services to help your business.

Our team of chartered accountants have a wealth of experience in a broad range of sectors, from construction and property to the charity sector.

If you want to learn more about how the team can help or simply want some tax advice from a trusted accountant, please contact us by filling in a contact form or calling 0161 962 1855.

Making Tax Digital for VAT: One month countdown begins

Making Tax Digital for VAT: One month countdown begins:

It is currently mandatory for most businesses with a taxable turnover above the £85k VAT threshold and will be mandatory for all businesses in April 2022. All VAT registered businesses must file their first VAT return for the VAT quarter starting on or after 1 April using MTD for VAT software. Our team at A&C Chartered Accountants have already moved across all of our clients using Xero and Sage software.

Xero calculates VAT and files VAT returns online securely with HMRC using software that’s compatible with HMRC systems. With Sage Business Cloud Leave your tax worries in the past. Collaborate with your accountant in the app or take control yourself. Anything’s possible with Making Tax Digital compliant VAT returns, ready to be submitted to HMRC with a single click.

Need more information?

Are you ready for Making Tax Digital for VAT?

If not, we can help. We offer a wide range of VAT services for your business.

Our team of chartered accountants have a wealth of experience in a broad range of sectors, from construction and property to the charity sector.

If you want to learn more about how the team can help or simply want some tax advice from a trusted accountant, please contact us by filling in a contact form or calling 0161 962 1855.

Changes to Accounting for VAT on Imports for Users of Flat Rate Scheme

There are important changes from 1 June 2022 for small businesses using the Flat Rate Scheme who are importing goods and using postponed VAT accounting.

Those businesses using the Flat Rate Scheme must currently add the value of imported goods to the total of all their supplies before they carry out the scheme calculation.

For VAT return periods starting on or after 1 June 2022, they should no longer include import VAT accounted for using postponed VAT accounting in their flat rate turnover. The VAT due on any imports should be added to box 1 of the return after completing the Flat Rate Scheme calculation.

HMRC have issued the following updated guidance:

Complete your VAT Return to account for import VAT – GOV.UK (www.gov.uk)


Importers not using the VAT Flat Rate Scheme

HMRC have also updated their guidance for VAT registered importers not using the Flat Rate Scheme:-

Complete your VAT Return to account for import VAT – GOV.UK (www.gov.uk)

These traders must account for postponed import VAT on their VAT returns for the accounting period which covers the date they imported the goods. The normal rules apply for what VAT can be reclaimed as input tax and the trader’s monthly statement will contain the information to support their claim.

HMRC is aware of the problems some importers are having when trying to access their monthly VAT statements. If you cannot access your statement or you’re having problems when viewing your statement, you should follow the guidance on how to complete a VAT Return if you’re having problems with your monthly statements.

As long as you take reasonable care to follow the guidance, there will be no penalty for errors.

Need more information?

We offer a wide range of VAT services to help your business.

Our team of chartered accountants have a wealth of experience in a broad range of sectors, from construction and property to the charity sector.

If you want to learn more about how the team can help or simply want some tax advice from a trusted accountant, please contact us by filling in a contact form or calling 0161 962 1855.

A Guide To Government Tax-Free Childcare Accounts

Raising a family is full of many unforeseen expenses. For new parents, the cost of childcare, in particular, can be a shock. And although there isn’t much in the form of financial support for parents, there are schemes which can help.

One such example, and the focus of this article, is the Government’s Tax-Free Childcare Account. This scheme offers parents a 25% top-up on childcare costs, which can be used for everything from nursery fees to after-school clubs and registered childminders. So, if you’re looking for a way to ease the financial burden of childcare, setting up a tax-free childcare account could be the solution. In this guide, we’ll explain everything you need to know, including:

  • What is a tax-free childcare account?
  • How does it work?
  • Who is eligible?
  • Childcare vouchers vs tax-free childcare accounts

What Is A Tax-Free Childcare Account?

A tax-free childcare account is a savings account that parents and family members can contribute towards to help pay for childcare. I know what you’re thinking, “So what, I can just set aside money in my bank account”.

But the bonus with the government’s scheme is that it offers parents a 25% top-up on whatever they add to the account – helping make childcare more affordable. The account can be used to pay for nursery fees, breakfast and after-school clubs, summer camps and OFSTED registered childminders.

How Does A Tax-Free Childcare Account Work?

The scheme operates by topping up savings of up to £8,000 per child by 25%. Parents can use the money to spend on qualifying childcare.

So, for every £8 paid into an online account, the government adds an extra £2, up to a limit of £2,000. For example, for childcare costs of £500 per child per month, the family would pay £400 into their childcare account and the government would pay in £100 per child. This would be an annual saving of £1,200 per child.

The scheme generally applies to children under 12. In the case of disabled children, the age limit is 16 and the amount that can be saved is £16,000 a year, topped up by the government by 25% to a potential total of £20,000.

Even better, it doesn’t need to be the child’s parents paying into the account. Any family member can also make payments: uncles, aunts, grandparents and others.

Opening a tax-free childcare account is quick and easy and can be done at any time of the year. Money can be deposited at any time to be used straight away, or whenever it is needed. Unused money in the account can also be withdrawn at any time – making it quite a flexible account should you need the cash for something else.

Who Is Eligible?

Undoubtedly, the scheme sounds like a great opportunity for working parents. However, there are some eligibility requirements to consider.

The scheme is available to both employees and self-employed individuals, unlike the traditional childcare voucher scheme offered by some employers. Your family could be eligible if:

  • You have a child or children aged 11 or under. They stop being eligible on 1st September after their child’s 11th birthday. If their child has a disability, they can receive support until 1st September after their child’s 16th birthday.
  • You earn, or expect to earn, at least the National Minimum Wage or Living Wage for 16 hours a week, on average.
  • Each parent earns no more than £100,000 per annum.
  • You do not receive tax credits, Universal Credit or childcare vouchers.

Positively, the account can also be used at the same time as the 15 or 30 hours of free childcare in England.

As it stands, the government are concerned about the lack of take-up of tax-free childcare accounts, with HMRC estimating that less than 22% of families eligible for the scheme had joined by March 2021. HMRC are suggesting that employers should make their employees aware of the support available to families with young children. With many parents working from home for part of the week, tax-free childcare accounts are more flexible than childcare vouchers.

Childcare vouchers continue to be available for employees who joined a qualifying scheme before 4 October 2018 and applies to children up to age 16.

Childcare Vouchers vs Tax-Free Childcare Accounts

If your employer offers a Childcare Voucher Scheme, you cannot use both this and a Tax-Free Childcare Account. The two schemes are mutually exclusive, and employers must stop giving their employees childcare vouchers with income tax and NIC relief if the employee informs them that they’ve started using the Tax-Free Childcare scheme. It’s important to assess whether switching to a Tax-Free Childcare Account would be more beneficial for your family. So let’s take a quick look at the two…

Childcare Vouchers

Childcare vouchers were a government-backed scheme designed to help UK parents reduce childcare costs by allowing them to pay for childcare using their pre-tax salary. Employers offered the scheme as a salary sacrifice, meaning part of your salary was exchanged for childcare vouchers before tax and National Insurance deductions.

This effectively lowered your taxable income, providing savings on tax and National Insurance. Vouchers were issued electronically, which parents could then use to pay approved childcare providers directly.

You may have noticed we’re talking in the past tense here. The childcare voucher scheme was ended in October 2018, although those within voucher schemes continue to be eligible until their child is aged 16, provided their employer is willing to continue operating the scheme.

However, with many employees now working from home more often, as part of the post-COVID move to hybrid working, many families found that they were not using all of their vouchers and chose to leave the scheme. You may also be weighing up the same question.

Pros:

  • Income tax and NI savings: Taken from salary before tax, reducing taxable income.
  • Both parents eligible: Both employed parents can claim, potentially doubling savings.
  • Flexible usage: Can be saved up or used monthly for qualifying childcare.
  • Continued availability: Existing members can keep using it, even though closed to new applicants.
  • Longer coverage: The voucher scheme applies to children up to 16 years old, whereas the tax-free childcare account only applies to children up to 12.

Cons:

  • Closed scheme: No new entrants after October 2018.
  • Limited benefit: Savings capped; basic-rate taxpayers typically save up to around £933/year.
  • Employer-dependent: The employer must offer the scheme to continue benefiting.

Tax-Free Childcare Accounts

Tax-free childcare accounts will gradually replace childcare voucher schemes as no new voucher schemes can be set up after 4th October 2018.

Pros:

  • Higher potential savings: Government adds 25% top-up (up to £2,000 per child, per year).
  • Not employer-dependent: Accessible to self-employed and those whose employer doesn’t offer vouchers.
  • Available widely: Open to most families earning between minimum wage and £100,000 per parent annually.
  • Usable for multiple children: Up to £2,000 per year per child (up to £4,000 for disabled children).

Cons:

  • Both parents must be working: Minimum earning threshold required.
  • Cannot be used alongside childcare vouchers: You must choose one or the other.
  • Account management required: Regularly deposit and manage payments via an online account.

Need More Information?

Would you like further guidance on all of the tax-efficient schemes available to you? Or perhaps you would like advice on whether or not it would be beneficial to leave your employer’s Childcare Voucher Scheme?

Then why not speak to one of our team? We’re a local, family-owned firm of accountants, operating for 30 years in Manchester and the North West (learn more about us).

Our team work hard to create smart and effective tax-efficient solutions for individuals, families and businesses – helping you save money. If you want to learn more about how the team can help or simply want some advice from a trusted accountant, please contact us.

For further information on government childcare support, see: https://www.childcarechoices.gov.uk/